
New Resolution Promotes Investment in Renewable Energy Systems in Cuba
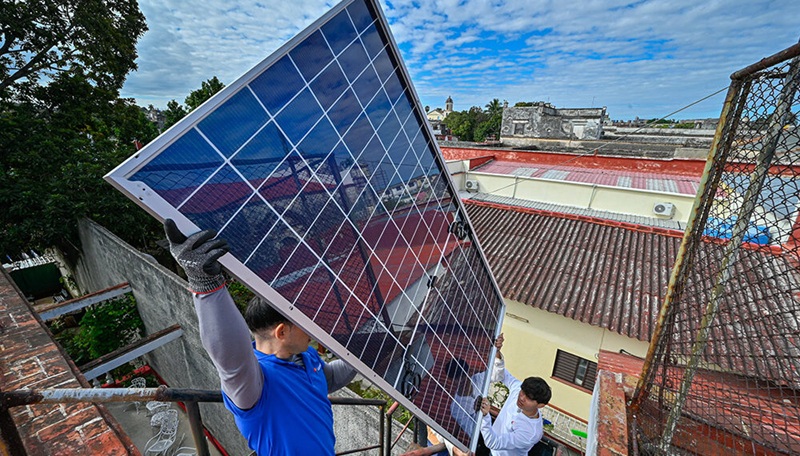
Foto ilustrativa: AFP
With the publication this Thursday of Resolution 41 of 2026 by the Ministry of Finance and Prices (MFP), the country introduces incentive measures for the importation, installation, and use of technologies from renewable energy sources.
According to information provided in a press conference by Yenisley Ortiz Mantecón, Deputy Minister of Finance and Prices, this regulation seeks to accelerate the energy transition in Cuba, benefiting individuals, legal entities, and all economic actors in general.
The new resolution is also part of the Government Program to correct distortions and re-energize the economy, where the recovery of the national electro-energy system and the diversification of the energy matrix are strategic axes.
"This resolution strengthens Cuba's commitment to energy sustainability, promoting self-sufficiency and reducing dependence on fossil fuels," stated the Deputy Minister.
Regarding the regulatory context, she noted that since Decree-Law 345 of 2017, the Cuban State has defined the development and efficient use of renewable energy sources as a priority, authorizing the granting of tax exemptions and rebates to those who invest in these technologies.
Based on that foundation, in 2023 and 2025, MFP resolutions were approved that refined the fiscal and tariff treatment, initially focused on legal entities and then progressively incorporating non-state actors and individuals.
As part of the Government's policy to support the recovery of the national electro-energy system and promote the transition toward the use of clean and sustainable technologies, it was decided to exempt individuals and legal entities from paying Customs Duty for the importation of photovoltaic solar systems, their fundamental parts and pieces, as well as solar water heaters; photovoltaic pumps; and small wind turbines.
Also included in the list are geomembrane biodigesters; biogas motor pumps; solar lighting; solar-powered air conditioning systems; chargers for electric vehicles that operate from the use of renewable energy sources; equipment intended for biomass processing for energy production; as well as the fundamental parts and pieces of these.
Referring to the resolution, the official commented that legal entities importing raw materials, components, parts, pieces, equipment, and accessories for executing an investment process or for manufacturing equipment, devices, or spare parts intended for the use of renewable energy sources are exempt from paying Customs Duty.
Furthermore, the state sector and non-state forms of management that execute electricity generation projects with clean sources or from the use of these are exempt from paying Customs Duty for the importation of machinery, equipment, and other necessary means during the investment process.
The exemption covers raw materials, components, and equipment intended for investment processes or the manufacture of renewable devices, as well as for state and non-state electricity generation projects.
The exemption is not restricted to equipment importation; it is also recognized when the project is for self-consumption or for sale to the National Electro-energy System, provided there is generation capacity available and technical conditions are met.
This means that the new resolution exempts legal entities and individuals carrying out economic activities, as applicable, who install renewable sources for their self-consumption or deliver energy to the National Electro-energy System, from paying Profits Tax and Personal Income Tax, in the amount of the investment value, during its recovery period and for a term of up to eight years.
Precisely, the novelty lies in the treatment of individuals carrying out economic activity (self-employed workers, agricultural producers, artists, intellectuals, and other forms of non-state management), who are exempt from personal income tax for the investments they make in renewable sources.
An indispensable requirement to access the tax benefit is that the taxpayer has a pre-feasibility study and obtains an opinion from the National Office for the Rational Use and Control of Energy (ONURE), which certifies the use of renewable sources in the project and determines the estimated period of investment recovery.
With these documents, one goes to the National Tax Administration Office, which implements the exemption.
Add new comment